Single-family permits sink
Builders brace for winter chill.
November 18, 2026
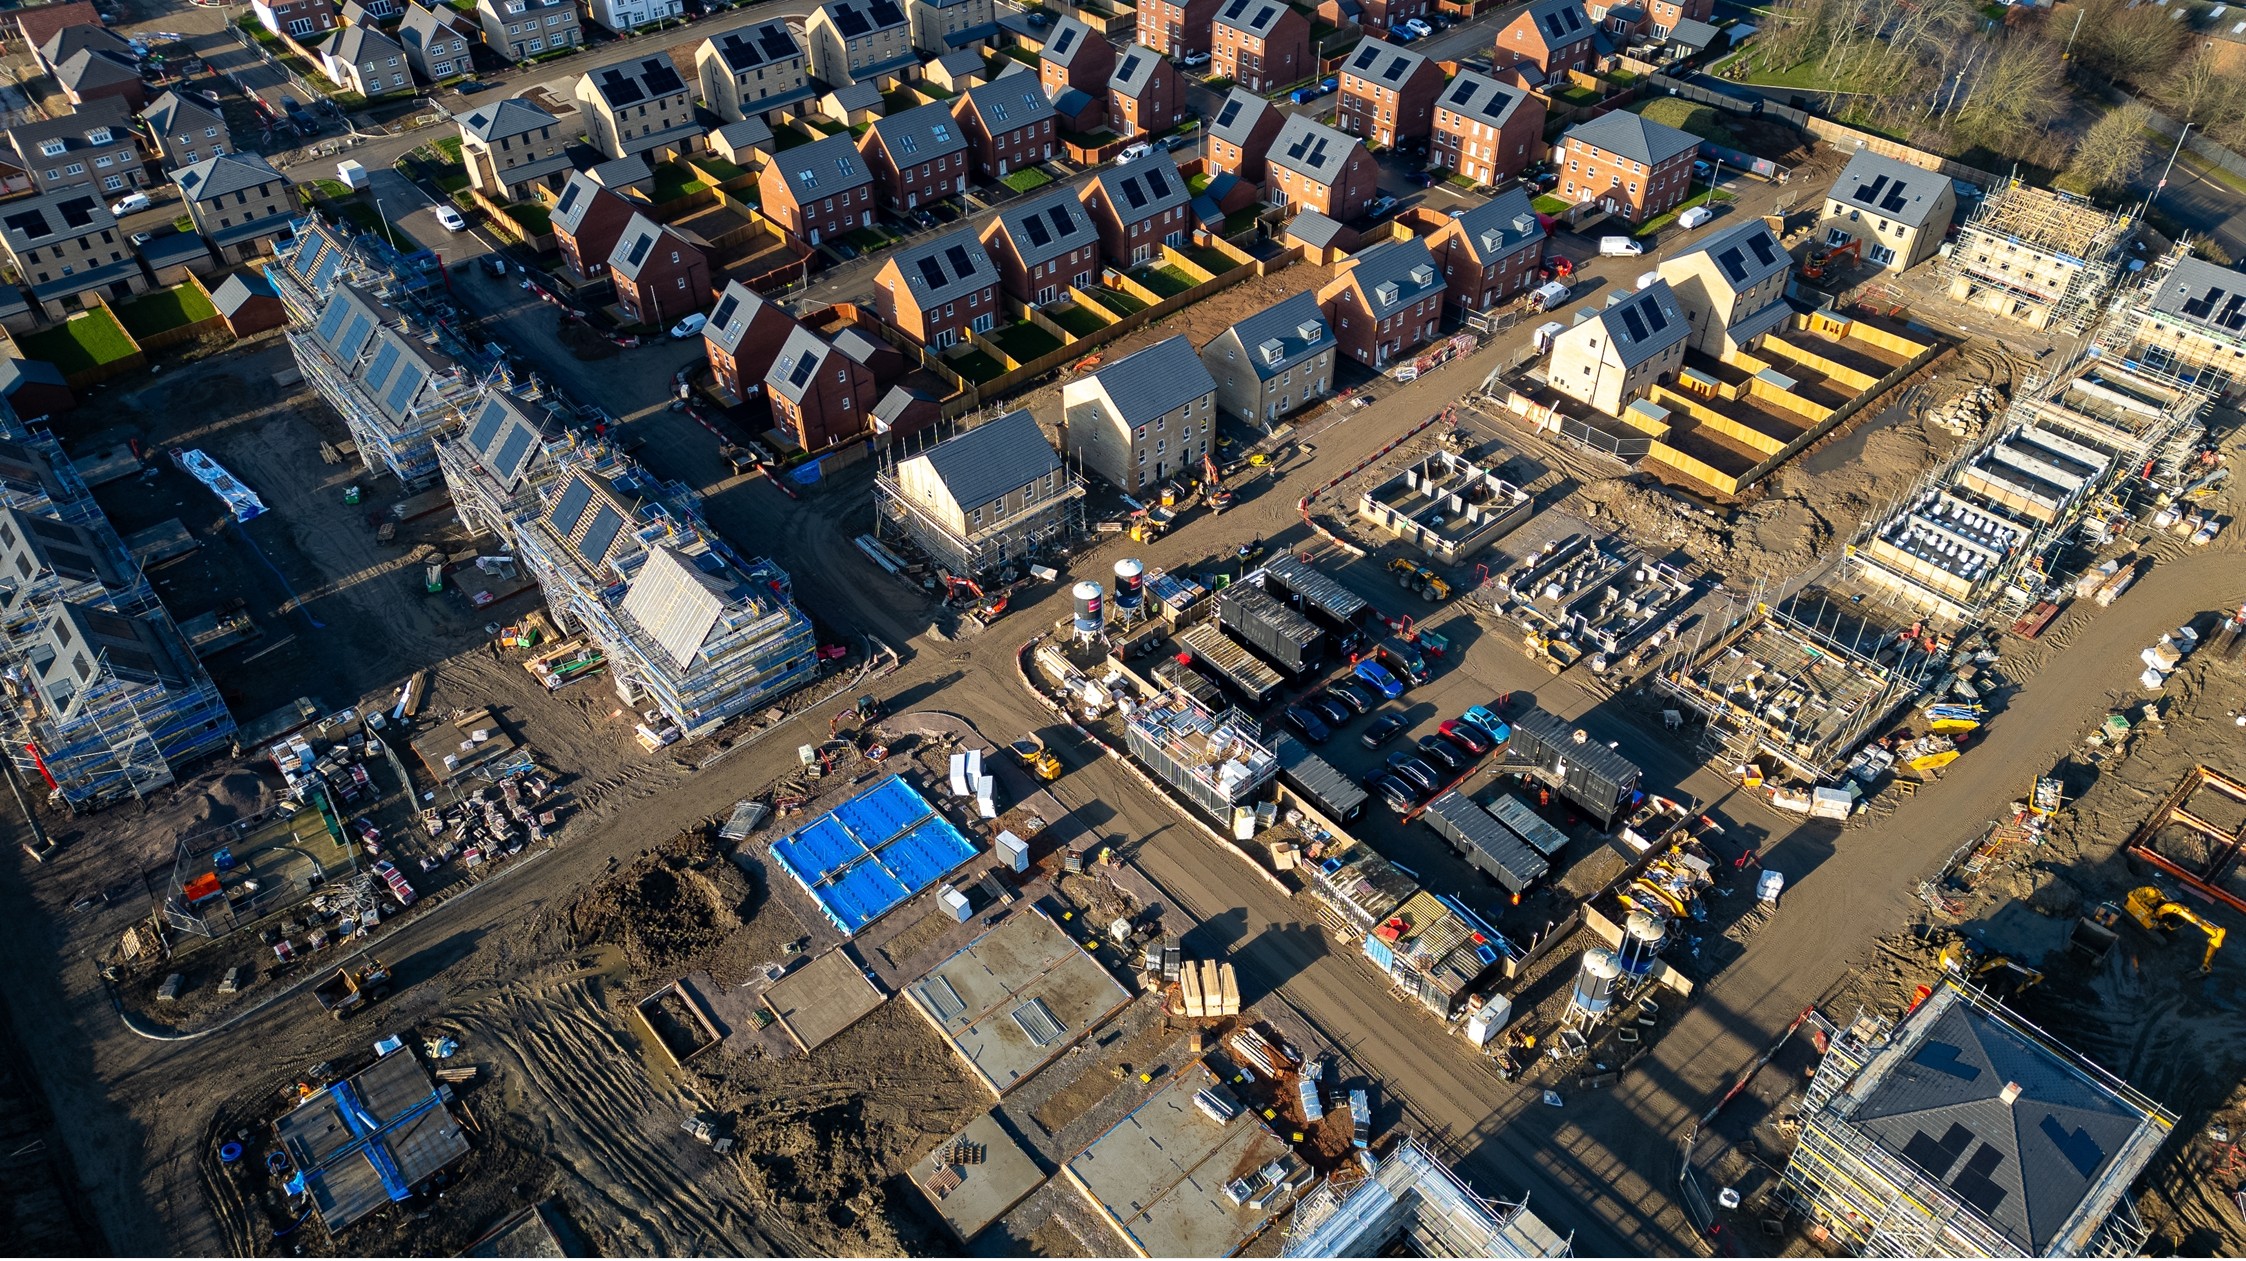
Housing starts rose 9.9% in October to a seasonally adjusted annual rate of 1.3 million, 2.8% above the year-ago level. The gain came after September was revised down to 1.19 million from 1.22 million. The South and Midwest posted gains, while the Northeast and West declined. Weather across the country was unseasonably mild in October, which could have contributed to gains in construction during the month. The data are seasonally adjusted and can be boosted when weather conditions are not the norm for the time of the year.
Single-family starts rose 4.0% to 864,000 after September was revised down to 831,000. Three of four regions posted gains; only the Midwest slipped. Single-family starts remain 3.2% below a year ago. The three-month moving average fell 0.4%, its sixth consecutive monthly decline.
Multifamily starts jumped 25.5% to 433,000 for buildings with five units or more, led by the Midwest. The series is noisy and extremely volatile. The three-month moving average, a better gauge, fell 4.2%.
Building permits, an indicator of future construction activity, fell 7.4% to 1.3 million in October, the lowest level since May 2020 and 8.7% below a year ago. Single-family permits dropped 8.7% to 772,000, the lowest since January 2023, and fell in every region. Multifamily permits fell 5.2% to 475,000. Single-family permits are now running well below single-family starts. Builders are breaking ground on homes they already had approvals for, without replacing them. The backlog of homes authorized but not yet started fell 3.5% to 276,000 after reaching a 22-month-high in September.
Total home completions rose 6.5% to 1.27 million but remain 10.4% below the year-ago level and are down 12.3% year-to-date. Single-family completions rose 6.3% to 900,000. Multifamily completions rose 9.0% to 362,000 but are 9.0% below a year ago.
Sentiment among home builders fell four points to 25 in November, the lowest level since April 2012, according to the National Association of Home Builders. Anything below 50 on the index is considered pessimistic. We are moving closer to the lows hit in the aftermath of the subprime mortgage crisis. Current sales conditions fell to 28, and six-month sales expectations slipped to 30. Buyer traffic dropped to 16, the weakest in 15 years outside of the onset of the pandemic. Hard to sell to buyers that do not show up.
The loss extends the downdraft we saw in October and the challenges that builders are facing due to everything from elevated mortgages rates to escalating materials costs – up at a double-digit pace from last year – and an inability to compete for scarce labor. The skilled trades have faced years of older workers retiring, without training new workers following the housing bust, a disproportionate reliance on immigrant labor and competition with much deeper pockets among data center builders.
Our own analysis of skilled labor in the most data-center intensive states revealed a large premium for skilled tradespeople; the sweeteners that hyperscalers can offer to lock in crews make it even tougher for builders to compete for those workers. Many overlap or can get certified to get the higher pay hyperscalers are willing to shell out. Credit conditions for land and construction loans tightened for a 19th consecutive quarter in the third quarter, with effective rates on loans for speculative single-family construction near 12%.
The share of builders cutting prices rose to 46%, the most since the pandemic, with the average discount holding at 6% for an eighth straight month. Sixty-eight percent of builders offered incentives, also the most since the pandemic.
Mortgage rates have eased for four straight weeks but remain above the psychologically critical 7% threshold. The 30-year fixed rate mortgage averaged 7.11% in the week ending November 12, down from 7.40% in mid-October but well above 6.24% a year ago. Existing resale inventory climbed to a 5.1 months' supply in October, the most since 2015. That adds competition for builders trying to move new homes. We expect the Federal Reserve to raise rates again in December, followed by additional hikes in the spring of 2027.
The recession in housing is over two years in the making and residential investment will remain a drag on growth into 2027.
Yelena Maleyev
KPMG Senior Economist
Bottom Line:
The bounce in October starts came on the back of a downward revision to September and did little to change the trend. Mild weather may have contributed to those gains. The polar vortex, the ring of frigid air that circles the Arctic, was disrupted earlier this month than at any time on record. That raises the odds of Arctic blasts across parts of the US around Thanksgiving and into early December, though a strong El Niño could soften some of the chill. Any cold snap would add insult to injury for an already frozen housing market. Permits are the better guide to what comes next and are not encouraging as they dropped across every region. Builders are working through approvals already in hand and not replacing them, which points to even fewer starts early next year. The recession in housing is over two years in the making and residential investment will remain a drag on growth into 2027.
Explore more

Subscribe to insights from KPMG Economics
KPMG Economics distributes a wide selection of insight and analysis to help businesses make informed decisions.
Meet our team