Builder confidence sinks to 2012 level
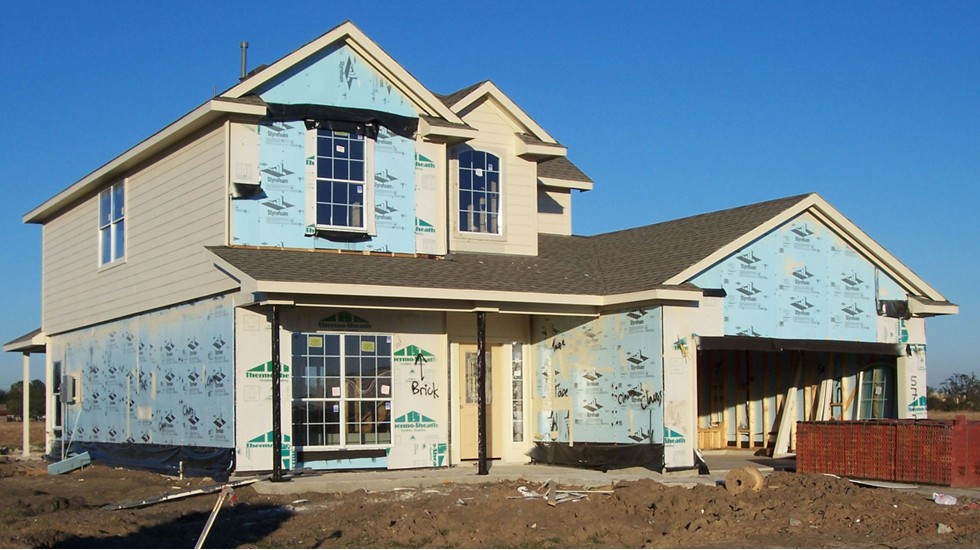
Rising mortgage rates close the door on new building.
October 20, 2026
Housing starts fell 5.2% in September to a seasonally adjusted annual rate of 1.2 million. That is 7.4% below the year-ago level and the second weakest pace of the year. August starts were revised up to 1.3 million. The Midwest and West posted the steepest declines, while the Northeast came in flat and the South posted a gain.
Single-family starts fell 4.6% to 859,000, the lowest in a year. Single-family starts were revised lower in August, even as multifamily starts were revised up. Only the Northeast recorded an increase. The three-month moving average fell 1.6%; it has declined in four of the last five months. Builders are holding off on introducing new supply as they focus on selling the inventory they have on hand.
Multifamily starts fell 7.2% to 349,000 for buildings with five units or more. This series is noisy. The three-month moving average, a more accurate gauge of the direction in the multifamily market, fell 12.4%. Only the South racked up a gain in multifamily construction in September. Rents have begun to rise in many parts of the country, as absorption of the overhang apartments has picked up. Those who cannot buy often rent, which has buoyed demand for apartments.
Building permits, an indicator of future construction activity, were nearly unchanged from August at 1.4 million in September. That is still down 3.0% from a year ago. Single-family permits fell 4.0% to 845,000, the lowest level since April 2023. Multifamily permits rose 5.9% to 503,000, the highest since February. The backlog of all homes authorized but not yet started held at 279,000, 9.8% above a year ago.
Total home completions rose 2.2% to 1.2 million but remain 14.0% below the year-ago level. Single-family completions dropped 2.4% to 840,000, below the level of single-family starts for the second consecutive month and the lowest level since May 2020.
Multifamily completions rose to 339,000 but were still down a sharp 20.4% from a year ago. The wave of apartment deliveries that held down rents in high-supply markets, especially in the Sunbelt, has thinned out. The new apartment permits will not translate into finished units for well over a year.
Sentiment among home builders fell three points to 29 in October, the lowest level since June 2012, according to the National Association of Home Builders. That dates to the misery home builders experienced attempting to emerge from the subprime housing bust and underscores how difficult conditions have become for builders. Anything below 50 is considered pessimistic. Current sales conditions fell to 33, also the lowest since 2012, while six-month sales expectations dropped five points to 32. Buyer traffic fell five points to 18, the lowest since April 2012, excluding the onset of the pandemic. The share of builders cutting prices jumped to 43%, up from 38% in September and the highest share since at least 2020. The South, the largest home building region, fell to 27.
Mortgage rates continued to climb. The 30-year fixed rate mortgage averaged 7.40% in the week ending October 15, unchanged from the prior week but up from 6.95% in mid-September. The jump came at the start of the fall selling season. Bond yields are now well above the level we saw when the Federal Reserve hit a peak in rates in 2023 and have begun to take on a mind of their own in a world awash in debt. The Fed raised rates in September and is expected to do so again in December. Markets have priced in three more hikes by year-end 2027 in response to the persistence of inflation.
The share of builders cutting prices is the highest since at least 2020.
Yelena Maleyev
KPMG Senior Economist
Bottom Line:
Mortgage rates above 7% have pushed builder confidence and buyer traffic back to levels last seen in 2012, while the share of builders cutting prices is the highest since at least 2020. Builder margins are getting hit, as competition for everything from scarce labor to materials is intensifying; tariffs and rising fuel costs have added insult to injury. Brace for more pain in the housing market as we move into the end of the year.
Explore more

Subscribe to insights from KPMG Economics
KPMG Economics distributes a wide selection of insight and analysis to help businesses make informed decisions.
Meet our team