

Your essential guides to financial statements
Our Guides to financial statements help you to prepare financial statements in accordance with IFRS Accounting Standards.
- Illustrative disclosures, which illustrate one possible format for financial statements, based on a fictitious multinational corporation.
- Disclosure checklists, which identify the disclosures that may be required based on currently effective accounting standards.
- Supplements to Illustrative disclosures, which illustrate additional disclosures that companies may need to provide on accounting issues.
Preparing for initial application of IFRS 18

Our Illustrative disclosures guide now reflects initial application of IFRS 18 Presentation and Disclosure in Financial Statements. The guide illustrates early adoption of IFRS 18 but may be helpful to any company applying the accounting standard for the first time.
For more detail and resources on IFRS 18, please see our IFRS 18 hub.
Preparing for 2026 financial statements
The following publications are prepared under currently effective IFRS Accounting Standards, including IAS 1 Presentation of Financial Statements.


Illustrative disclosures
Disclosure checklists
Key considerations
The following considerations are important when preparing financial statements.
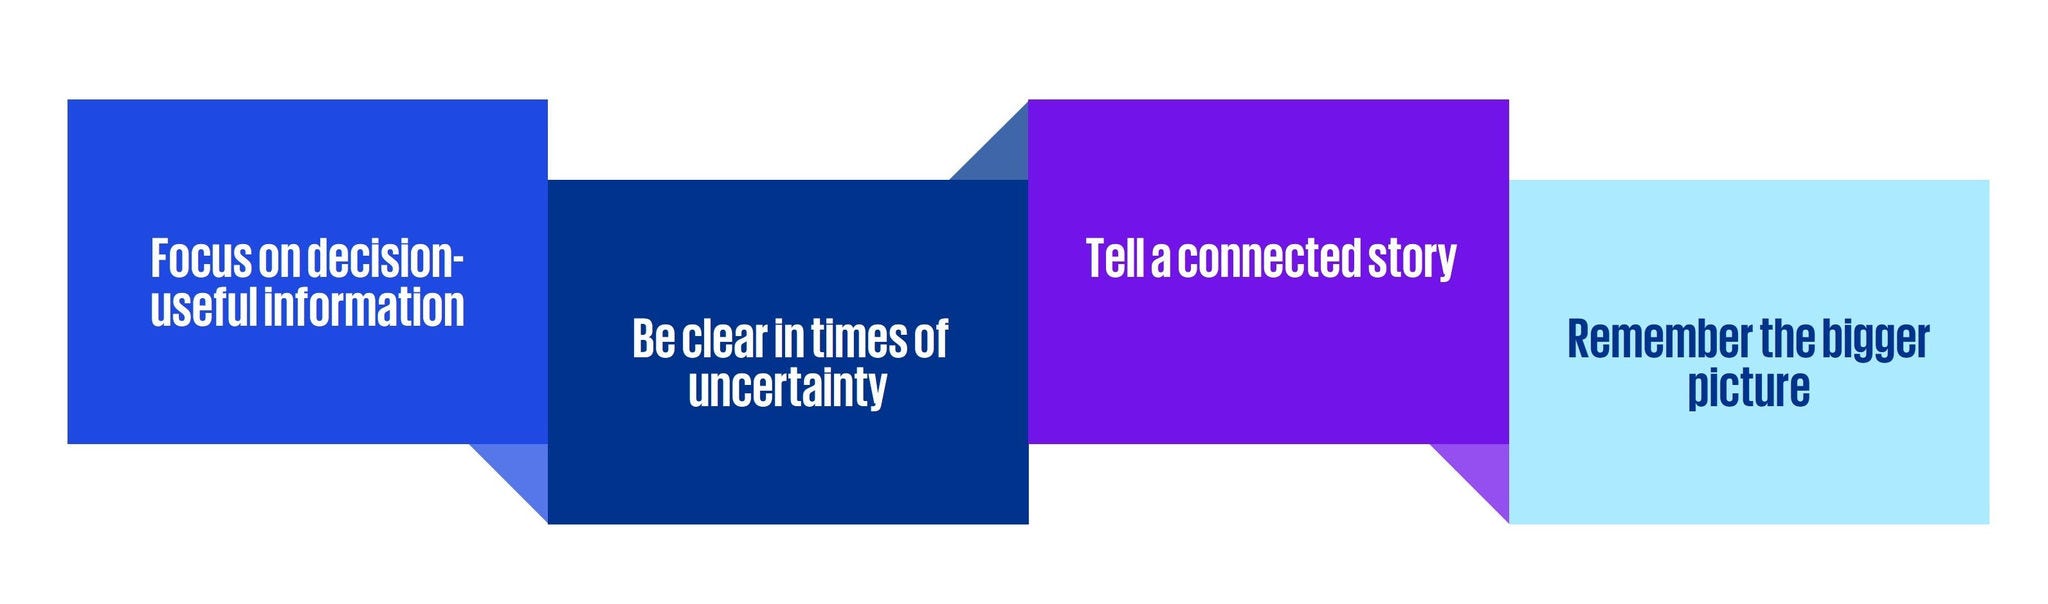
Investors, regulators and other report users rely on the financial statements to provide decision-useful information. They look for clarity in the annual (or interim) report and expect the financial and non-financial information to be connected. This is especially important when reporting on issues that create volatility for the company’s prospects – e.g. climate-related matters and other uncertainties.
What's new in 2026?
The annual and the interim guides to financial statements are prepared under currently effective IFRS Accounting Standards, including IAS 1 Presentation of Financial Statements. They reflect IFRS Accounting Standards in issue at 20 March 2026 that are required to be applied by a company with an annual reporting period beginning on 1 January 2026.
If you are applying IFRS 18 for the first time, please see our new Illustrative disclosures guide illustrating the initial application of IFRS 18 Presentation and Disclosure in Financial Statements, which is effective from 1 January 2027.
Annual financial statements – 2026 reporting periods
The 2026 Illustrative disclosures illustrate the financial reporting impacts of the following newly effective amendments.
Amendment | Issues covered |
Classification and Measurement of Financial Instruments – Amendments to IFRS 9 and IFRS 7 |
|
Contracts Referencing Nature-dependent Electricity – Amendments to IFRS 9 and IFRS 7 |
|
Interim financial statements – 2026 reporting periods
The 2026 Interim illustrative disclosures also reflect the requirements of the newly effective amendments. These amendments do not introduce any new disclosures that are explicitly required in the condensed interim financial statements. However, companies need to consider providing additional disclosures if they judge them to be material to understanding their financial position and performance in the interim reporting period.
In addition, our article Interim financial statements - Assessing the impact provides guidance for companies facing financial reporting challenges during uncertain times.
1 The amendments also provide additional guidance on classification of financial assets, including those with contingent features. These amendments are not illustrated in our illustrative disclosures.
2 The amendments also include guidance on hedge accounting requirements for companies that hedge their purchases or sales of electricity using PPAs. These amendments are not illustrated in our illustrative disclosures.
© 2026 KPMG IFRG Limited, a UK company, limited by guarantee. All rights reserved.