

The draft legislation to implement Crypto-Asset Reporting Framework (CARF) and the amended Common Reporting Standard (CRS) in the Hong Kong SAR (Hong Kong) was passed by the Legislative Council on 4 November 2026. The CARF and amended CRS will take effect on 1 January 2027 and 1 January 2028 respectively.
Summary
Background
The Inland Revenue (Amendment) (Crypto-Asset Reporting Framework and Amended Common Reporting Standard) Bill 20261 (the Bill) was gazetted on 22 May 2026. The Bill sought to implement the following in Hong Kong:
- the CARF – a framework developed by the OECD requiring crypto-asset service providers to report on crypto-asset transactions; and
- amendments to the existing CRS framework, namely (i) an expanded scope of reportable assets, (ii) additional reporting obligations and (iii) strengthened due diligence requirements2.
Subsequently, the HKSAR Government proposed various amendments3 (as Committee Stage Amendments or CSAs) to the Bill in response to comments received from us and other stakeholders.
The Bill and all the proposed amendments were passed by the Legislative Council on 4 November 2026. The corresponding Amendment Ordinance is expected to be published in the Gazette on 13 November 2026.
Key amendments to the Bill
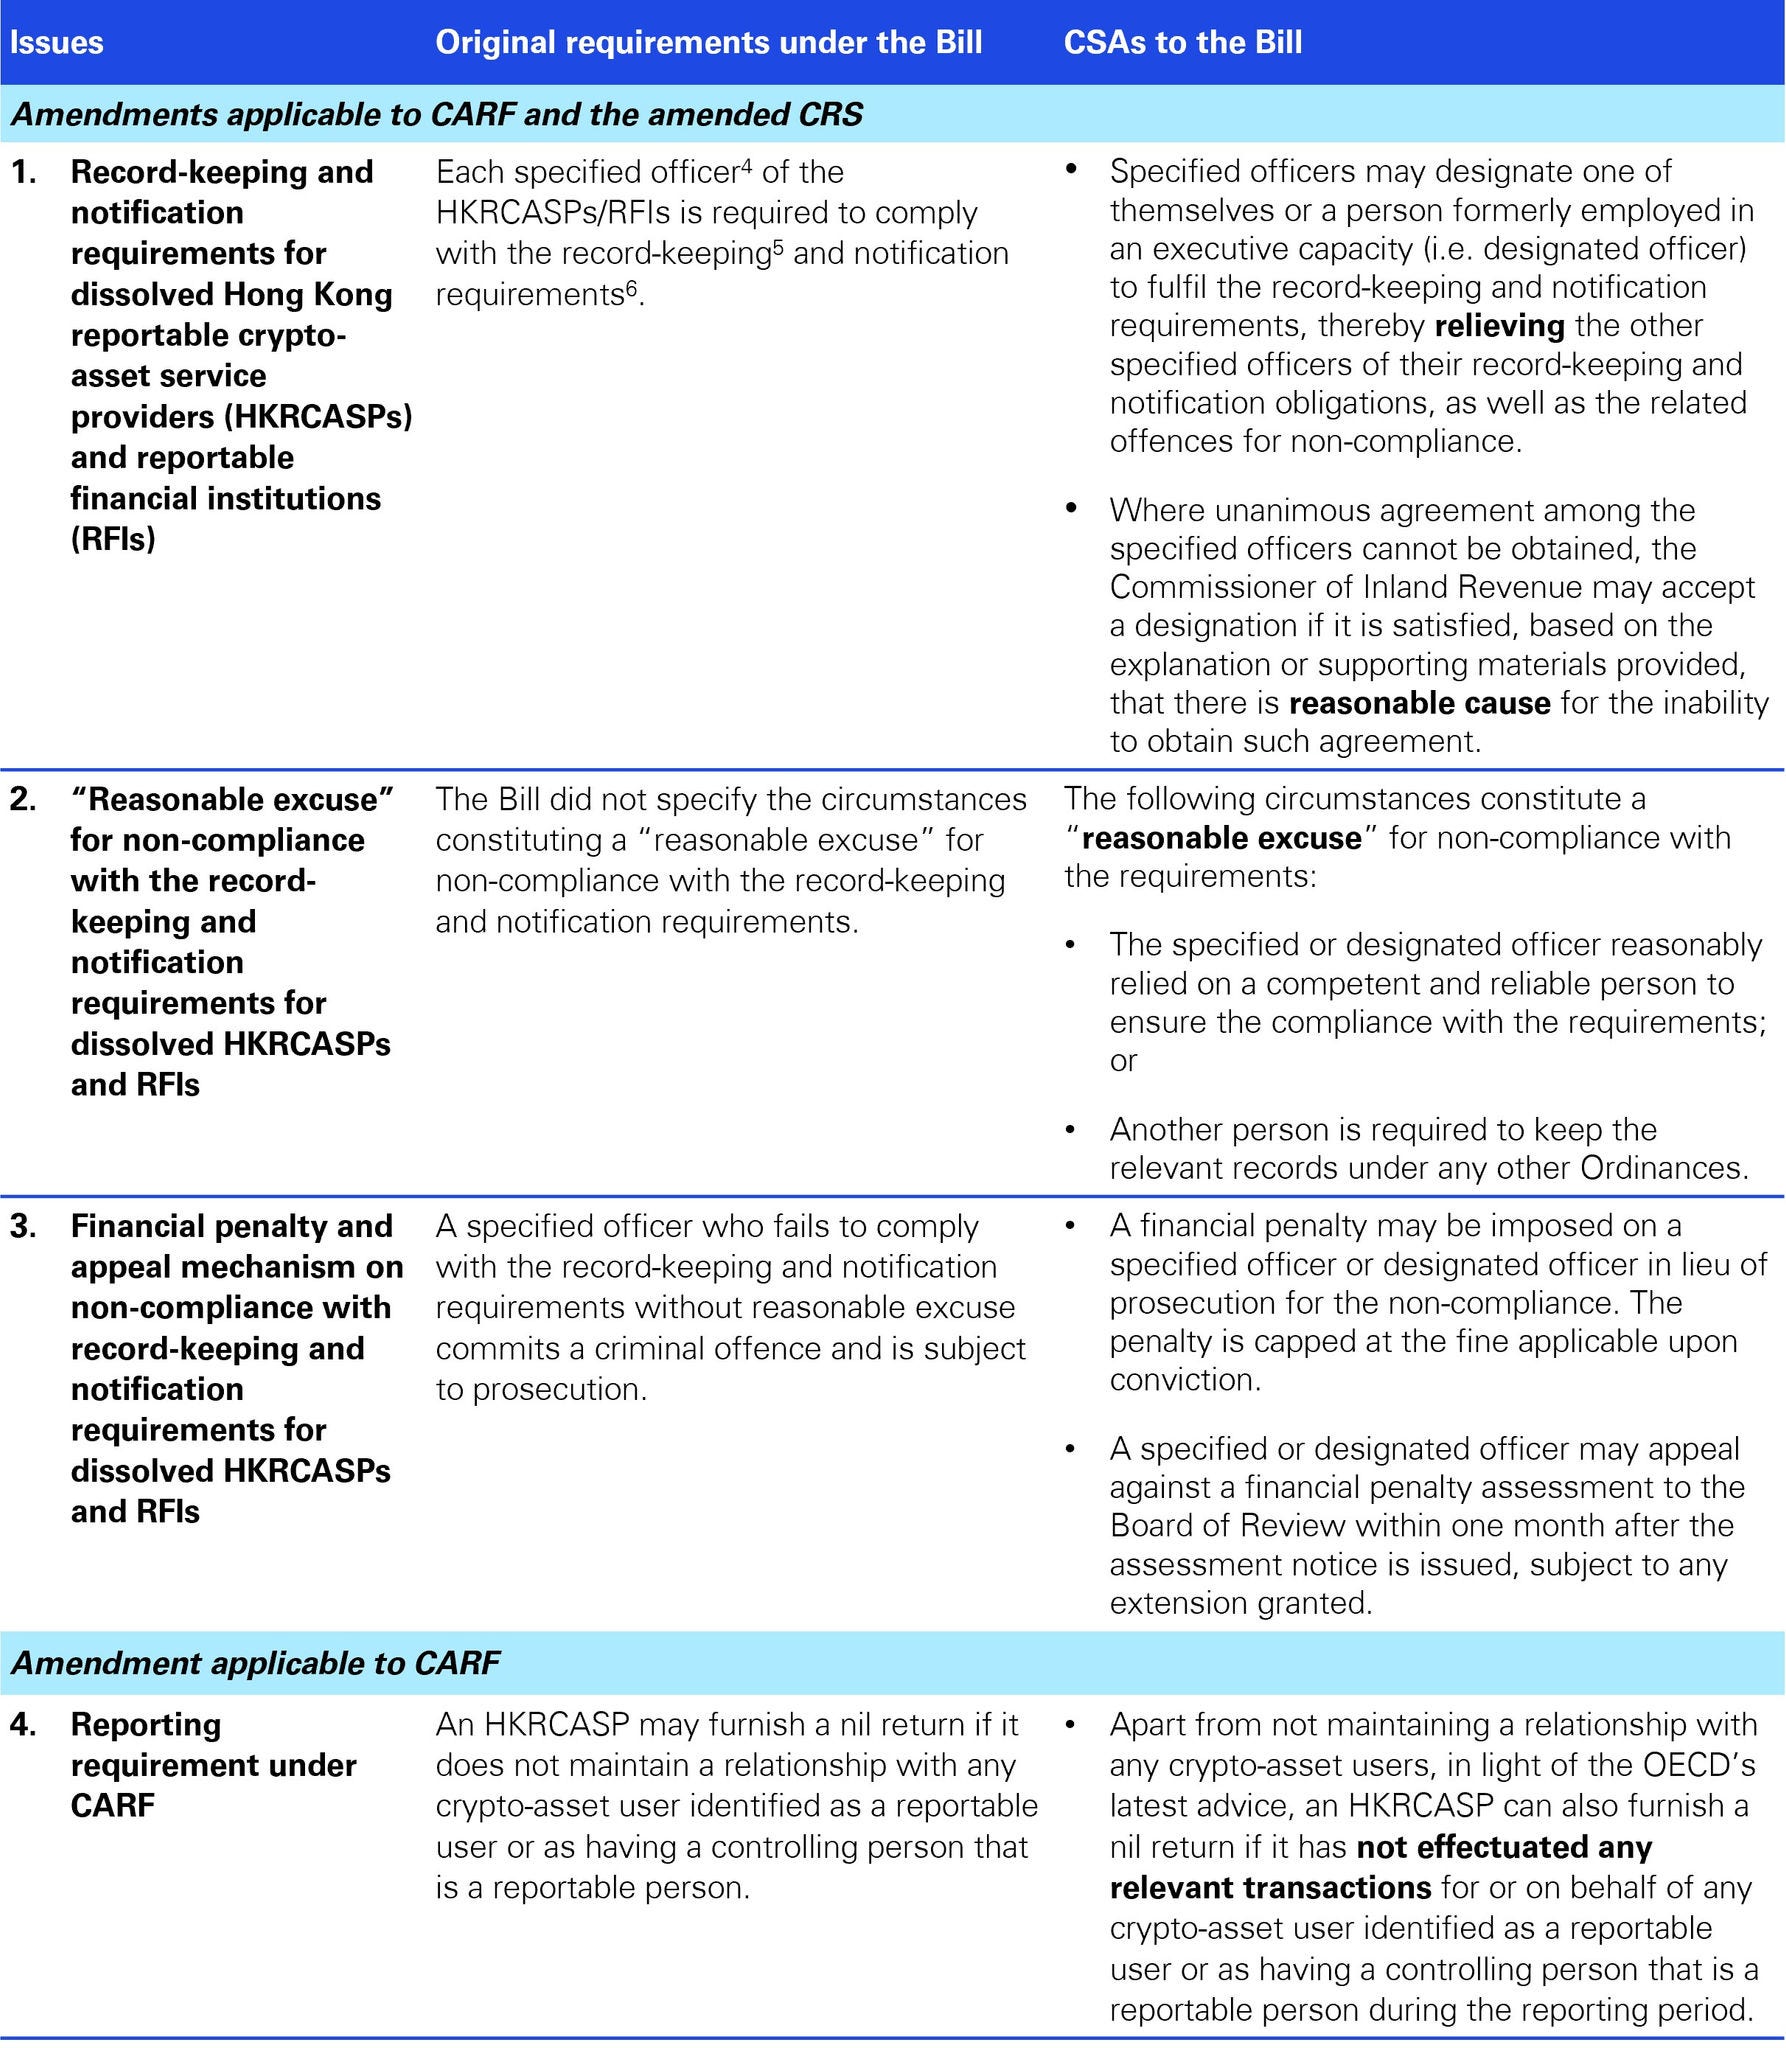
We highlight below the key amendments to the Bill. For a full list of CSAs, please refer to the Legislative Council paper issued by the Government3.
Commencement and implementation
CARF will take effect in Hong Kong on 1 January 2027, with the first reporting period covering the 2027 calendar year and the first automatic exchange of information expected in 2028. The amended CRS will take effect in Hong Kong on 1 January 2028, with the first automatic exchange under the amended standard expected in 2029.
The CSAs relating to the post-dissolution record keeping and notification obligations applicable to the specified or designated officers of RFIs and the corresponding penalty and appeal mechanism (i.e. items 1 to 3 in the above table) under the CRS framework will take effect in conjunction with the strengthened administrative framework for CRS7 (which was included in the Inland Revenue (Amendment) (Automatic Exchange of Information) Ordinance 20268) on 1 January 2027.
KPMG observations
With the expansion of international tax transparency frameworks, crypto-asset investors / users should consider whether their transactions are reportable under CARF and assess any associated local tax implications. At the same time, reportable persons under the amended CRS should reassess their tax residence and related reporting positions in light of the revised rules, particularly where existing arrangements may be affected.
On the other hand, with CARF taking effect in Hong Kong on 1 January 2027, crypto-asset service providers should assess whether they fall within the scope of the Hong Kong regime. In-scope HKRCASPs should review their products and consider whether they are regarded as crypto-assets, and get well prepared on their due diligence procedures and ensure their systems can capture the required transaction data in order to fulfil the reporting obligations under CARF. Looking ahead, HKRCASPs should stay tuned on any further developments on the practical implementation of CARF such as (i) how HKRCASPs are identified, monitored and governed and (ii) application of the Hong Kong nexus criteria for the purposes of the registration requirement.
Similarly, RFIs should prepare for the strengthened CRS administrative framework that will take effect from 1 January 2027, particularly the mandatory registration requirement, updated record-keeping requirement and strengthened sanctions for non-compliance. They should also review the implications of the amended CRS for their financial products, due diligence procedures and reporting systems ahead of its implementation on 1 January 2028.
If you have any questions or require assistance regarding the above developments, please feel free to contact us via taxservicesenquiry@kpmg.com.
1. The Bill can be accessed via this link: https://www.legco.gov.hk/yr2026/english/bills/b202605221.pdf
2. For more details, please refer to our previous Hong Kong SAR Tax Alert via this link: https://kpmg.com/cn/en/insights/2026/06/tax-alert-10-hk-draft-legislation-to-implement-carf-and-amended-crs-in-the-hksar-published.html
3. The full list of CSAs can be accessed via this link: https://www.legco.gov.hk/yr2026/english/bc/bc02/papers/bc02cb1-1261-1-e.pdf
4. Specified officers refer to directors of (or if there was no director, every person who was a trustee or responsible for the management of) the HKRCASPs/RFIs immediately before the dissolution.
5. This refers to the requirement to keep sufficient records (e.g. due diligence information) for a period of six years from the last day of the relevant reporting period or the return due date, whichever is the later.
6. This refers to the requirement to notify the Inland Revenue Department within one month of the dissolution or any change of contact details following such dissolution.
7. For more details, please refer to our previous Hong Kong SAR Tax Alert via this link: https://kpmg.com/cn/en/insights/2026/05/tax-alert-08-hk-draft-legislation-to-strengthen-administration-of-the-crs-in-the-hksar-published.html
8. The Ordinance can be accessed via this link: https://www.legco.gov.hk/yr2026/english/ord/2026ord004-e.pdf
Law passed to implement tightened reporting regime for financial accounts and crypto-assets in Hong Kong
Hong Kong SAR Tax Alert - Issue 20, November 2026

