
      Summary

      The HKSAR Government has proposed various amendments to the draft legislation on enhancing the tax concessions for funds, carried interest and family-owned investment holding vehicles (FIHVs) and provided clarifications on certain issues relating to the application of the enhanced tax concessions.

      In this tax alert, we summarise the key proposed amendments and clarifications relevant to the tax concession for FIHVs and share our observations. The key amendments and clarifications applicable to the tax concessions for funds and carried interest are discussed in a separate tax alert.
      Background

      The Inland Revenue (Amendment) (Preferential Tax Regimes for Funds, Family-owned Investment Holding Vehicles and Carried Interest) Bill 20261 (the Bill) was gazetted on 12 June 2026. The Bill set out detailed legislative amendments for implementing the enhanced tax concessions for FIHVs, funds and carried interest2 in the Hong Kong SAR (Hong Kong).

      Following the comments received from us and other stakeholders3, the Government has proposed numerous amendments (as Committee Stage Amendments or CSAs) to the Bill and provided certain clarifications on the FIHV tax concession sought by industry players4. 

      The key enhancements and clarifications

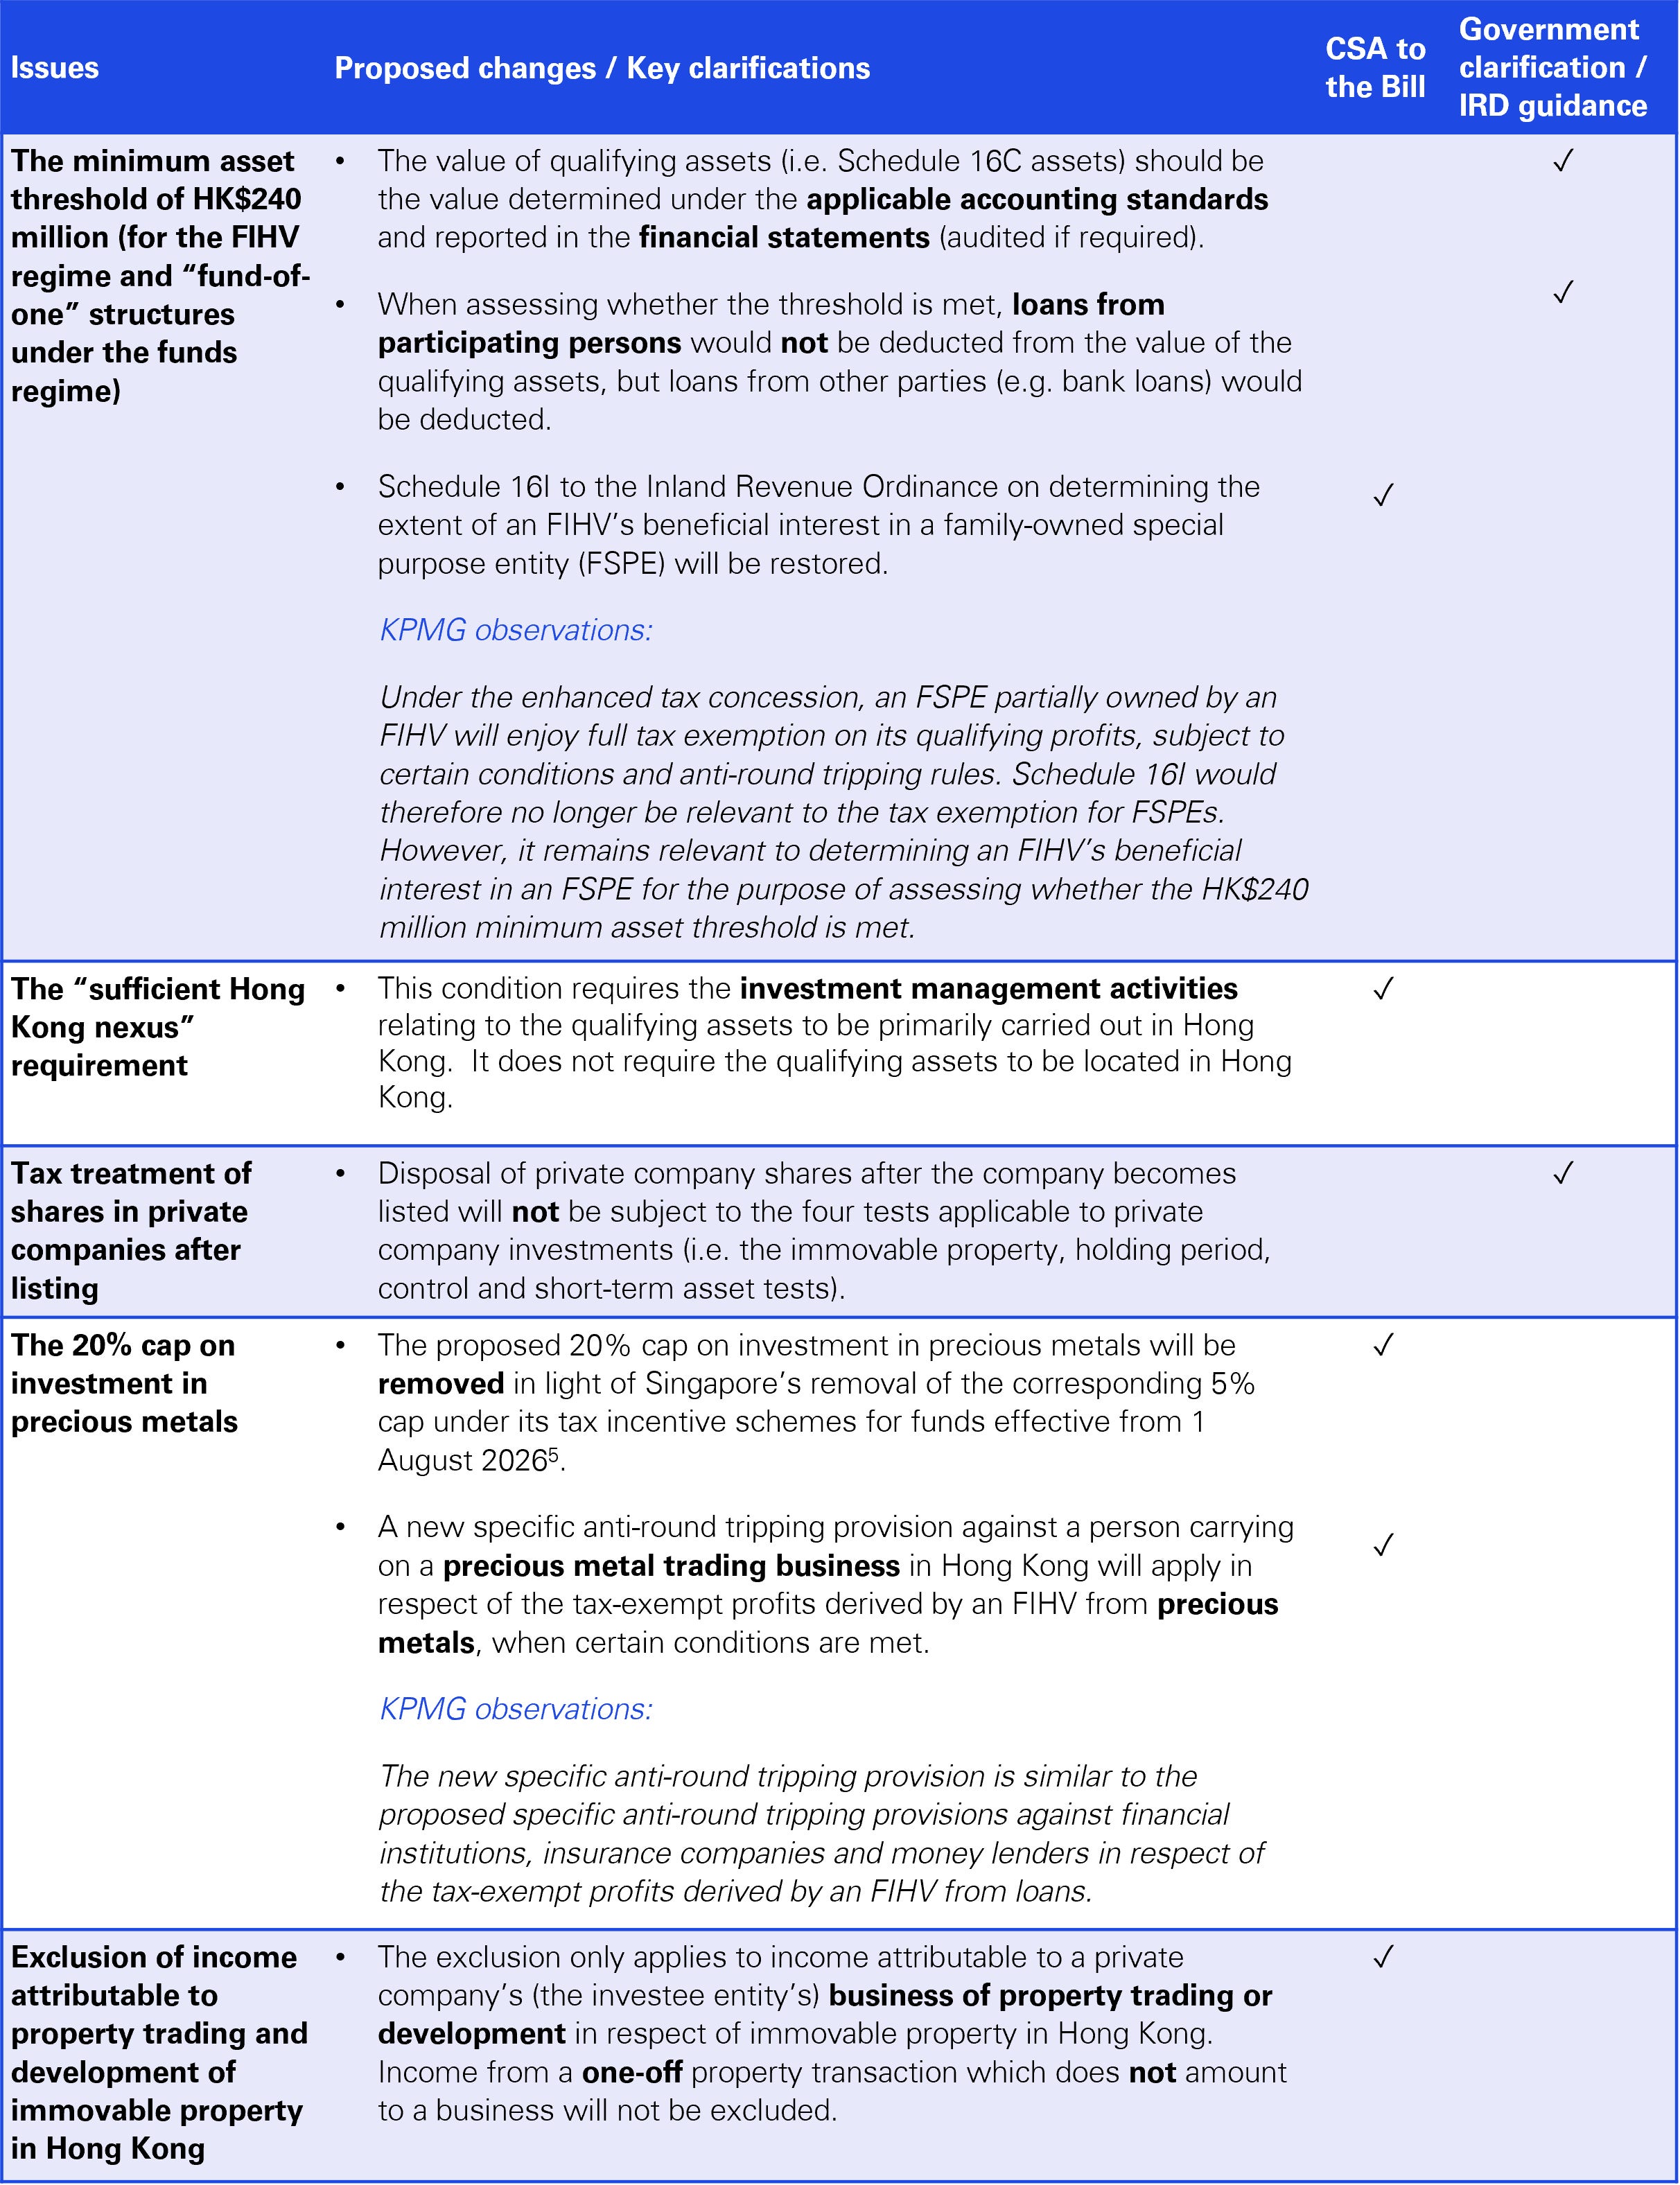
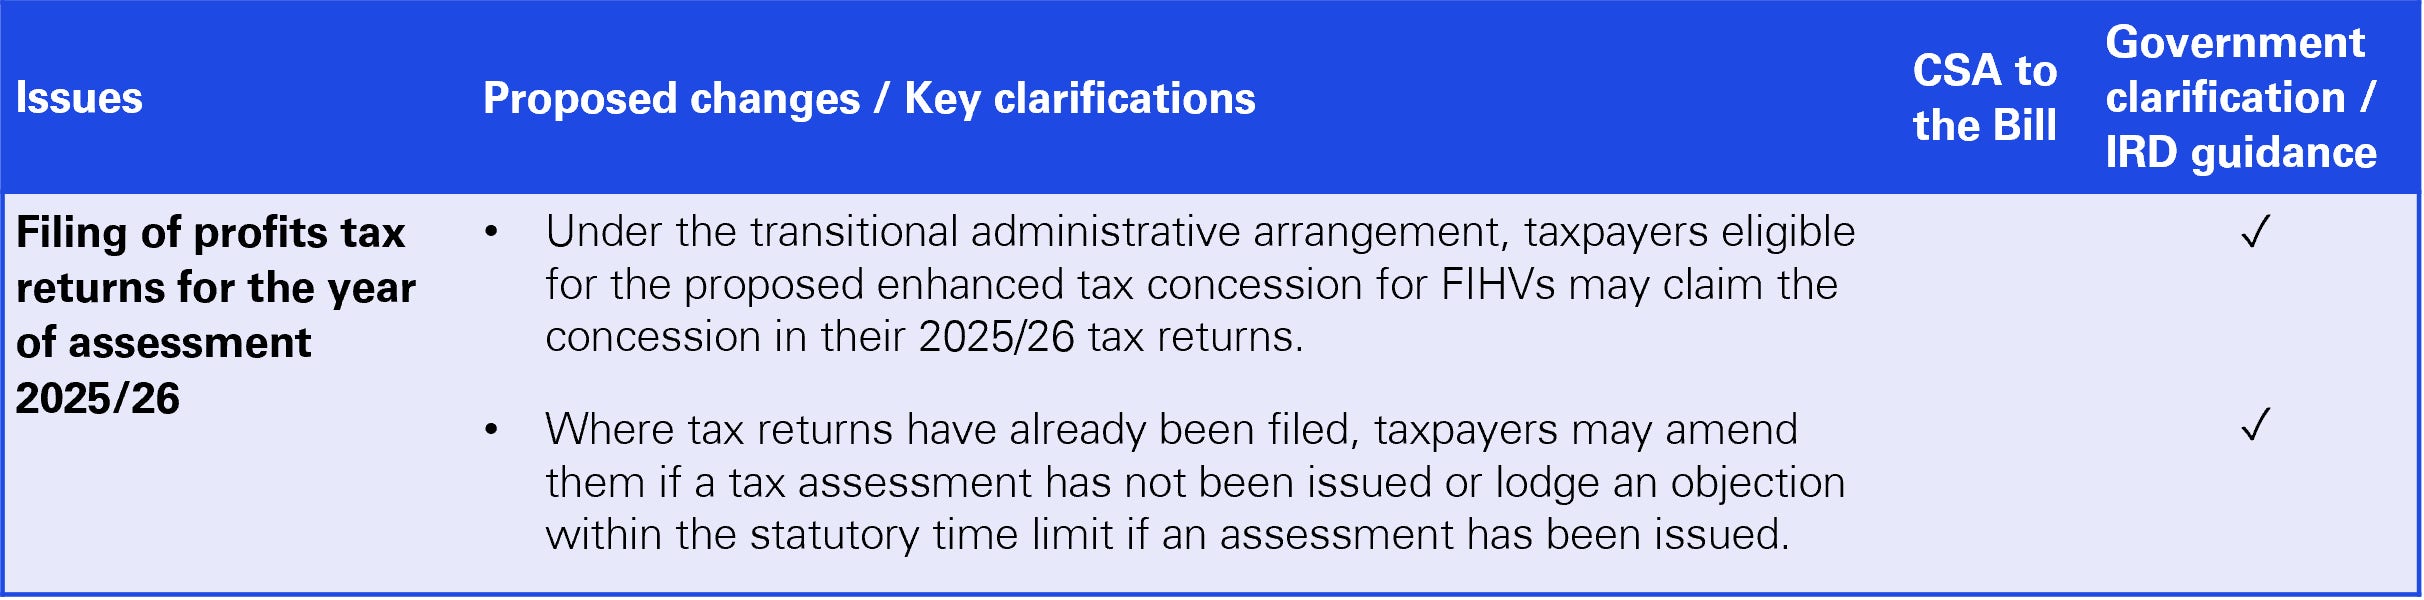
      The table below summarises the key amendments and clarifications that are relevant to the tax concession for FIHVs and indicates the means through which they will be implemented.


      KPMG observations

      The further refinements and clarifications to the family office tax regime in response to industry feedback are a welcome development. They should make the regime more attractive and practical for existing family offices in Hong Kong and those planning to establish a presence here, while providing greater clarity over its scope and application.

      That said, families wishing to benefit from the family office tax regime in Hong Kong should not consider the Hong Kong tax implications in isolation. Where relevant, the broader overseas tax implications of the proposed family asset-holding structures should be carefully assessed, including any potential Chinese Mainland tax exposures.

      While Hong Kong’s enhanced family office tax regime is intended to broaden the scope of qualifying investments and improve usability, cross-border structuring decisions still require a coordinated review of the applicable regulatory and tax rules in all relevant jurisdictions.

      If you have any questions or require assistance regarding the above developments, please feel free to contact us via taxservicesenquiry@kpmg.com.


      1. The Bill can be accessed via this link: https://www.legco.gov.hk/yr2026/english/bills/b202606122.pdf

      2. For more details, please refer to our previously issued Hong Kong SAR Tax Alert – Issue 11, June 2026.

      3. The submissions on the Bill can be accessed via this link: https://www.legco.gov.hk/en/legco-business/committees/bills-committee.html?2026&bc04#papers-and-reports&cat=d

      4. Please see the Government’s responses to the submissions on the Bill via this link: https://www.legco.gov.hk/yr2026/english/bc/bc04/papers/bc04cb1-1295-1-e.pdf

      5. For more details, please refer to the Circular issued by the Monetary Authority of Singapore in July 2026 via this link:

          https://www.mas.gov.sg/-/media/mas-media-library/schemes-and-initiatives/fdd/fdd-cir-052026-tax-incentive-schemes-for-funds-31-july-2026.pdf?utm


      Hong Kong SAR Tax Alert - Issue 18, October 2026

      Proposed refinements and key clarifications for the family office tax regime

      Hong Kong SAR Tax Alert - Issue 19, November 2026

      Hong Kong SAR Tax Alerts

      These are ad hoc newsletters covering topical tax issues in Hong Kong

      Submit RFP

      Find out how KPMG's expertise can help you and your company.