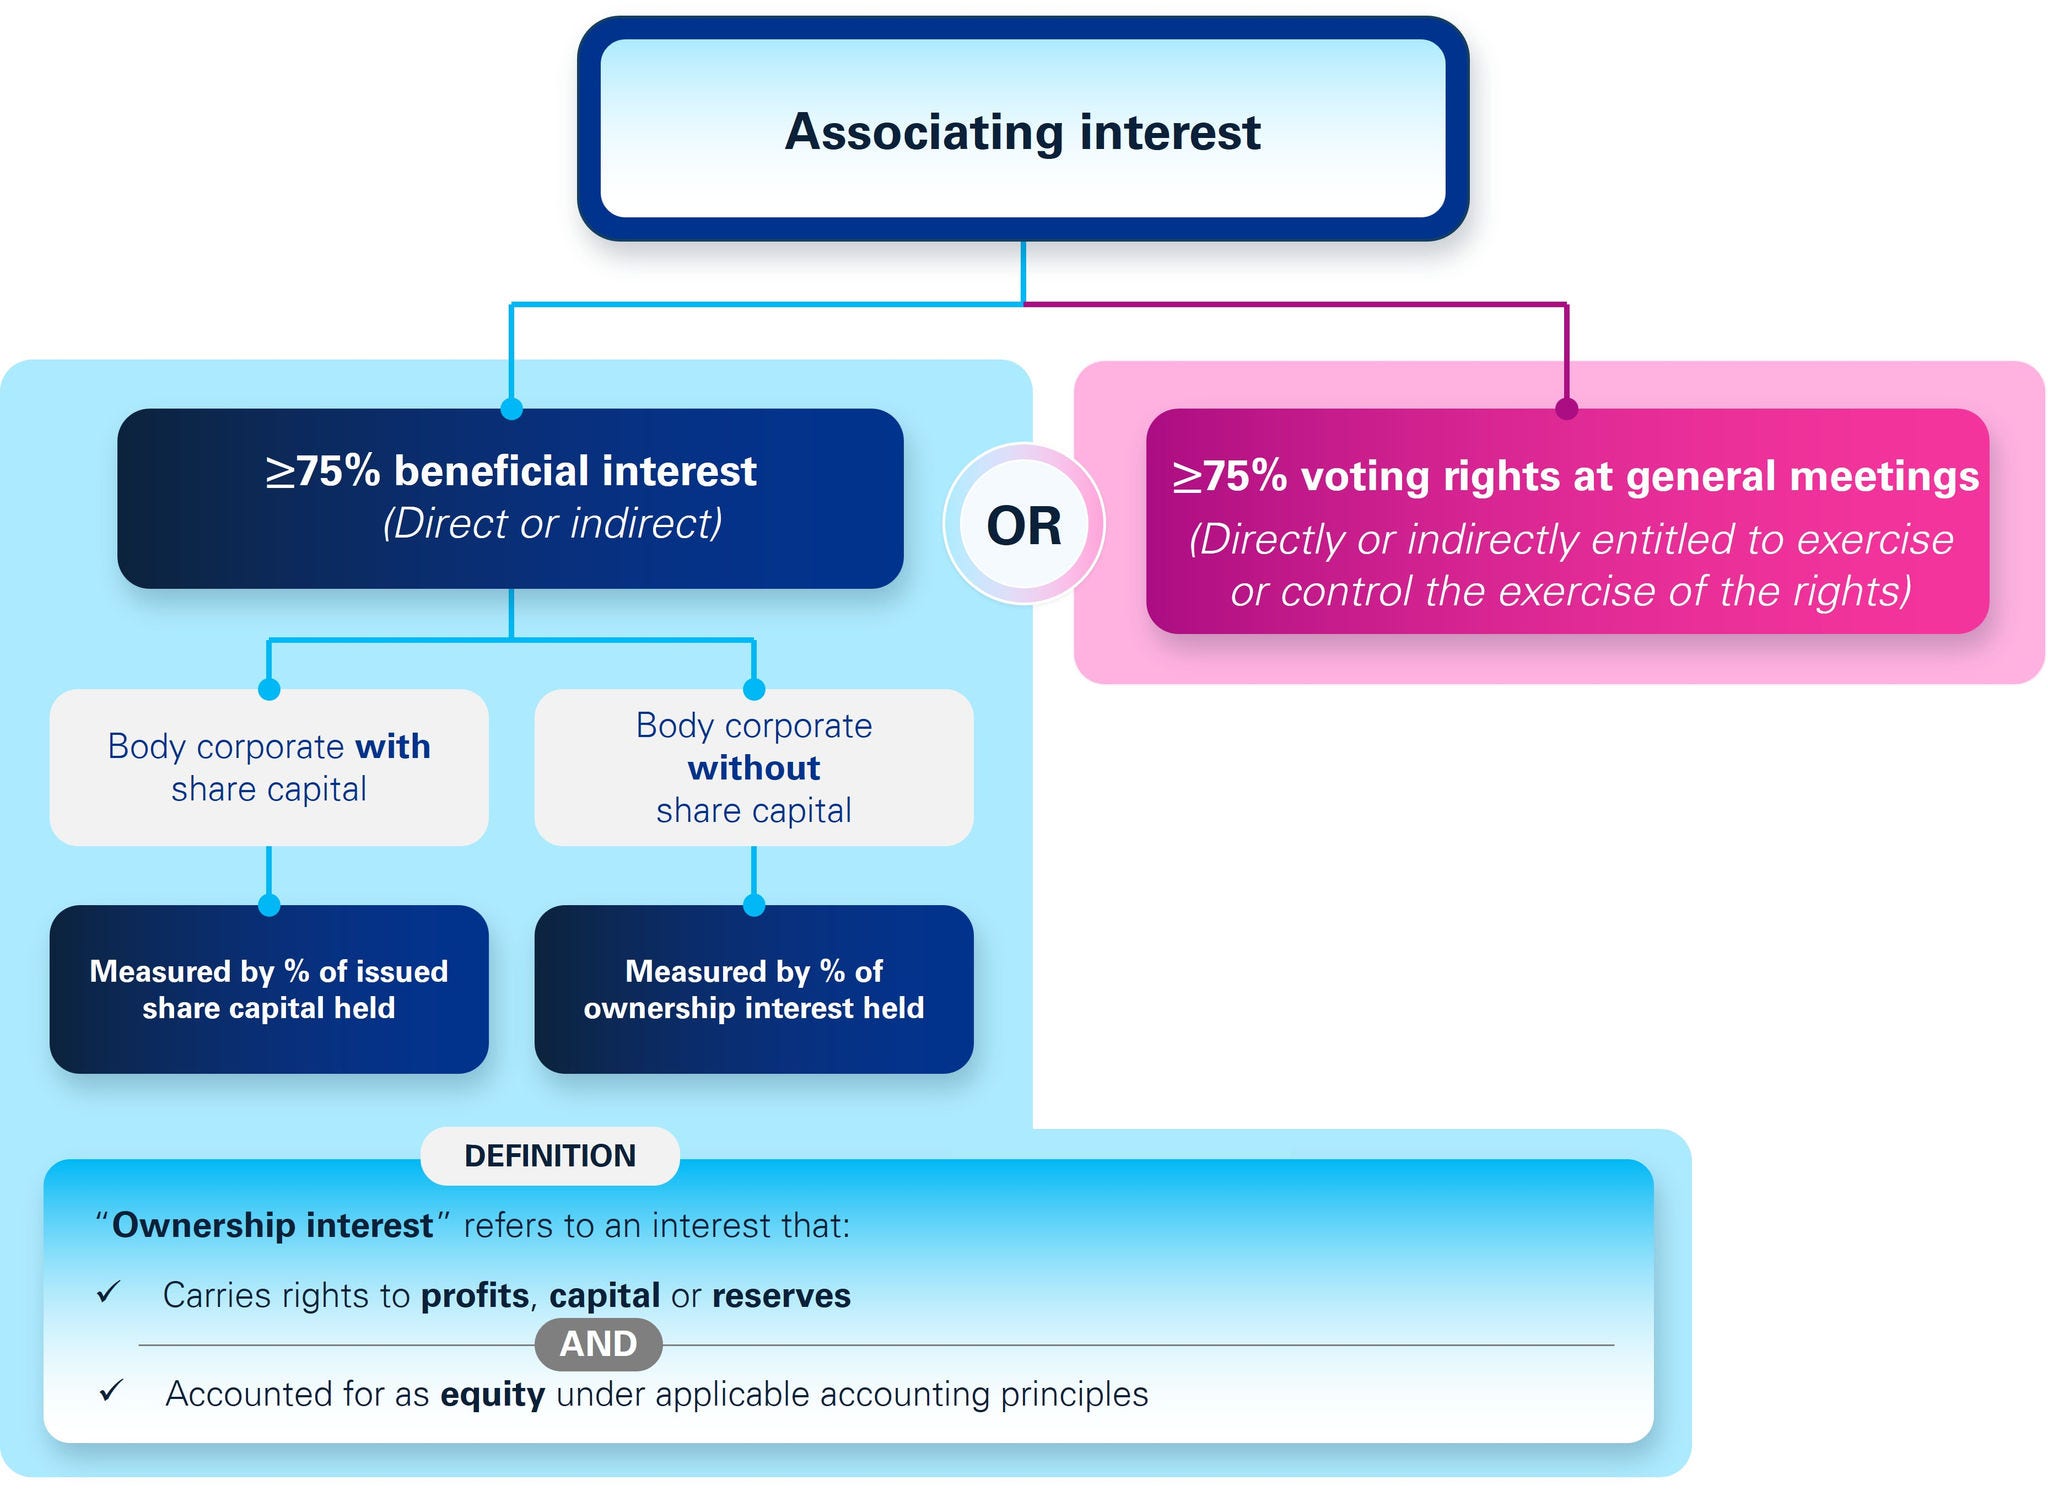
The draft legislation to implement the enhanced stamp duty relief for intra-group asset transfer under section 45 of the Stamp Duty Ordinance (the section 45 relief) was published in the Gazette on 2 October 2026. Subject to the enactment of the draft legislation, the enhanced section 45 relief applies to the relevant instruments executed on or after 25 February 2026.
In this tax alert, we discuss the key enhancements to the section 45 relief and share our observations.