

Valuation outcomes continue to be influenced by investors’ required returns and their expectations regarding future economic development. Determining appropriate expected returns remains particularly challenging amid uneven growth prospects, geopolitical uncertainty, fiscal pressures and rapid technological transformation.
These developments underscore the importance of understanding the interplay between observed market returns, long-term growth assumptions and implied expected returns.
In the 21st edition of our Cost of Capital Study, titled “The Discount Rate Puzzle: Navigating between Cost of Capital, Alphas and Premiums,” we analyze current developments in the cost of capital and valuation parameters in the DACH region.
The study focuses on the so-called “discount rate puzzle”, examining the application of different risk premiums and their appropriate incorporation into valuations without double counting of risk factors. It also addresses current developments in the economic environment and capital markets.
An overview of the key articles
- Theses on the current economic environment
- What lies behind the discount rate puzzle?
- Deep Dive Premiums: Where should risk premiums be reflected in valuations, and how can double counting of risk factors be avoided?

What is the Cost of Capital Study?
The KPMG Cost of Capital Study is an annual empirical survey that provides insights into how current economic developments affect the business models, corporate development and long-term return expectations (cost of capital) of companies in the DACH region (Germany, Austria and Switzerland).
The annual extensive reach of the KPMG Cost of Capital Study underlines the great practical benefit that this study offers for companies.
In the FAQs, you will find explanations of all capital cost parameters.
KPMG Cost of Capital Study 2026
Find out how companies adjust their cost of capital amidst the tension between falling risk premiums and rising interest rates.
Cost of Capital parameters 2026
WACC
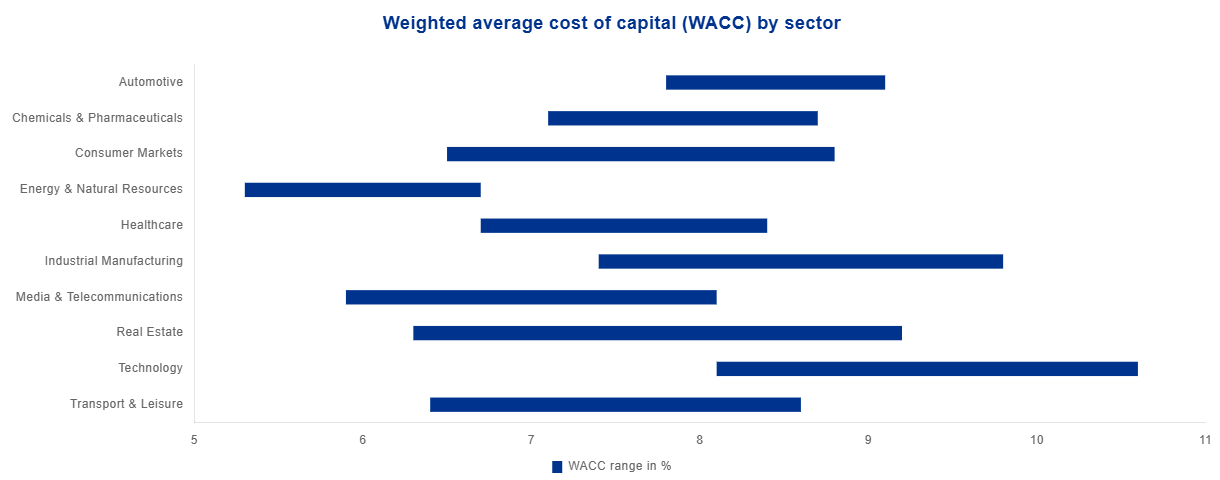
In the current reporting period, participating companies applied weighted average cost of capital (WACC) rates ranging from 5.3 percent to 10.6 percent. The overall average WACC across all industries stands at 7.9 percent, reflecting a decrease compared to the previous year’s figure of 8.5 percent.
Comparatively high average WACC values were reported in the Technology (9.4 percent), Industrial Manufacturing (8.7 percent) and Real Estate (8.4 percent) sectors. In contrast, the Energy & Natural Resources sector recorded the lowest average WACC at 6.5 percent, with Media & Telecommunications following at 7.0 percent.
Beta factor
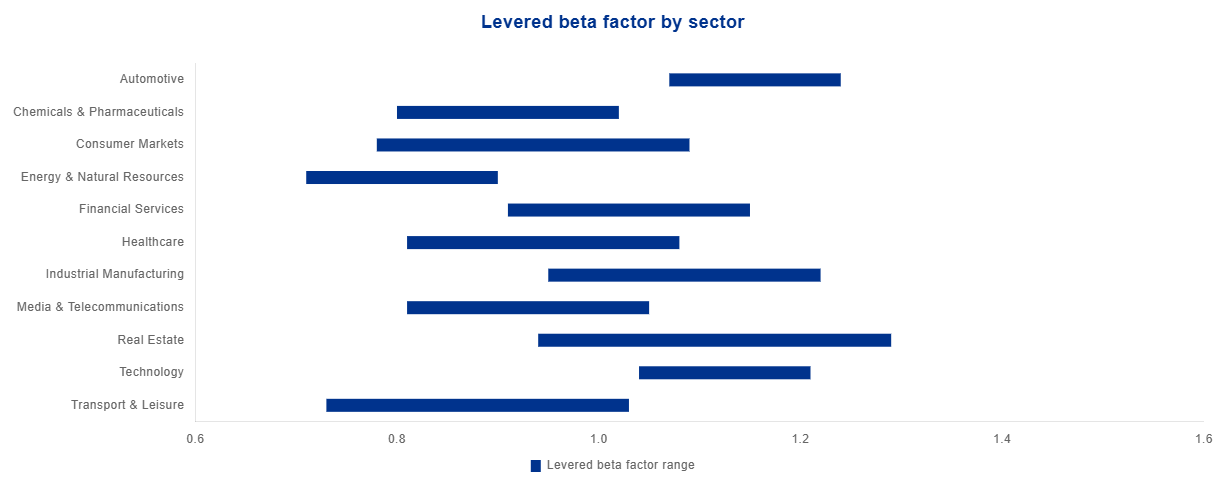
During the survey period, the levered beta factors of all participating companies ranged from 0.71 to 1.29, with an average of 0.99—below the previous year’s figure of 1.03.
The highest average levered beta values were observed in the Automotive sector (1.19), followed by Technology (1.14) and Real Estate (1.11). In contrast, the Energy & Natural Resources (0.81), Transport & Leisure (0.85) as well as Chemicals & Pharmaceuticals and Media & Telecommunications (0.90 each) sectors reported the lowest average levered beta factors.
 > Click on the image to enlarge it
 > Click on the image to enlarge it
Total return
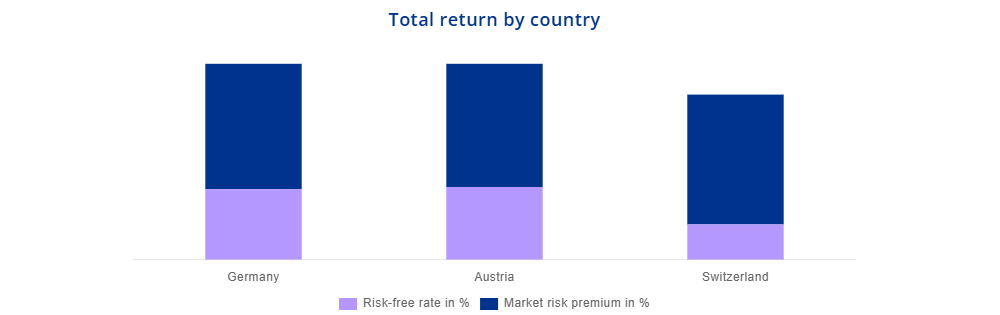
During the survey period, participating companies applied a risk-free rate of 3.2 percent in Germany and 3.3 percent in Austria (previous year: 2.5 percent each). In Switzerland, the average risk-free rate applied decreased to 1.6 percent (previous year: 2.6 percent).
Compared with the previous year, the average market risk premium applied by participating companies declined by 1.0 percentage points to 5.7 percent in Germany and by 1.1 percentage points to 5.6 percent in Austria. In Switzerland, the market risk premium decreased by 0.1 percentage points to 5.9 percent.
Based on these figures, the average expected total return during the survey period amounts to 8.9 percent in Germany and Austria and 7.5 percent in Switzerland.
Cost of equity
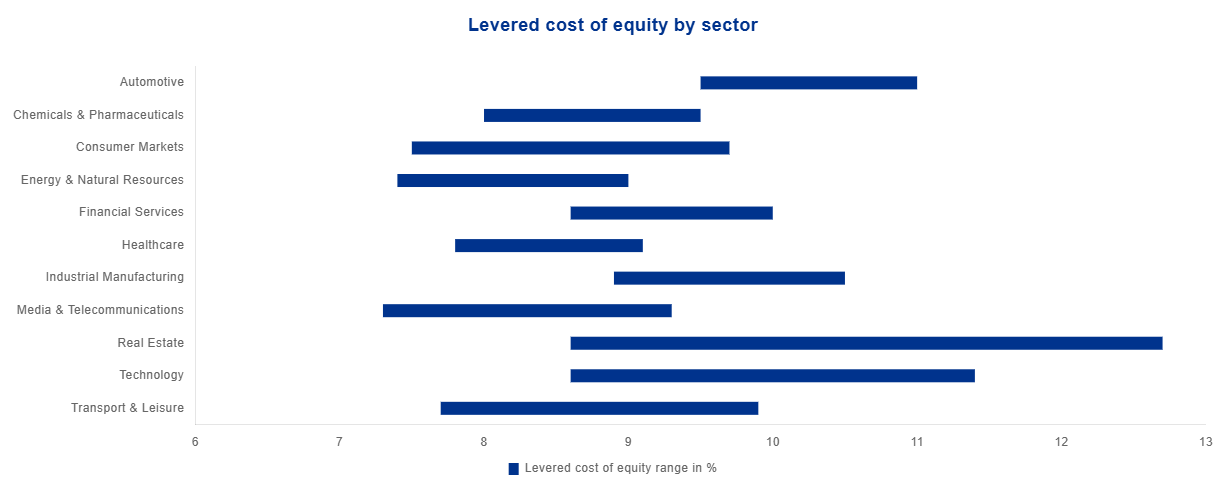
During the survey period, the levered cost of equity reported by participating companies ranged from 7.3 percent to 12.7 percent, with a cross-industry average of 9.1 percent—below the previous year’s figure of 9.7 percent.
The highest average levered cost of equity was observed in the Real Estate sector at 10.7 percent, followed by Automotive at 10.3 percent.
In contrast, the Energy & Natural Resources sector recorded the lowest average at 8.1 percent, followed by Transport & Leisure, Media & Telecommunications and Consumer Markets at 8.4 percent each.
 > Click on the image to enlarge it
 > Click on the image to enlarge it
Cost of debt
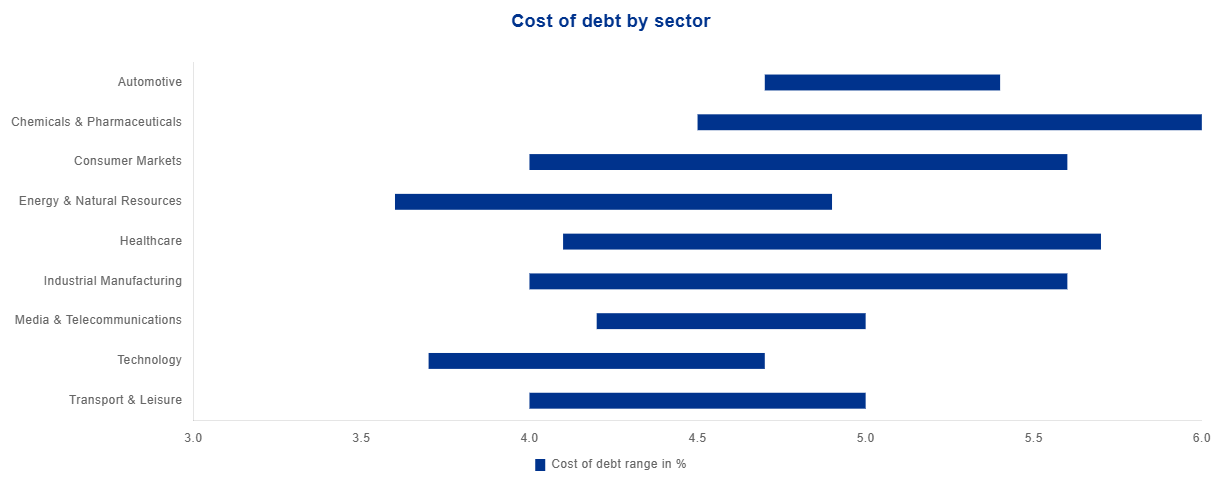
The cost of debt reported by participating companies during the survey period ranged across industries from 3.6 percent to 6.0 percent. On average, the applied cost of debt was 4.7 percent, representing an increase of 0.4 percentage points compared to the previous year.
The highest average cost of debt was recorded in the Chemicals & Pharmaceuticals sector at 5.4 percent, while the Energy & Natural Resources (4.0 percent) and Technology (4.1 percent) sectors reported the lowest average values.
Debt ratio
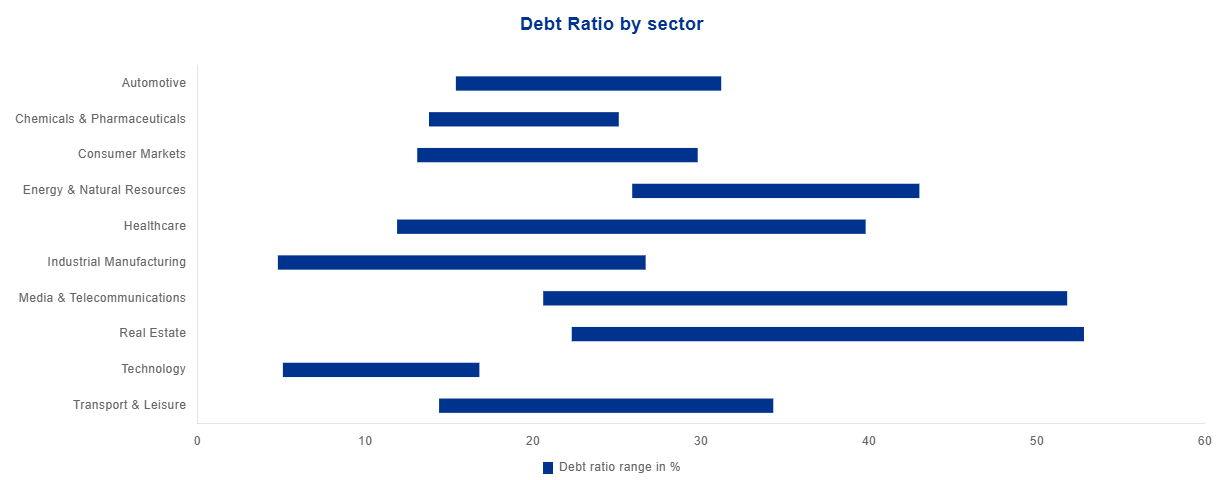
The debt ratios reported by participating companies vary significantly across industries, ranging from 4.8 percent to 52.8 percent. Across all sectors, the average debt ratio stands at 23.5 percent, unchanged from the previous year.
The Energy & Natural Resources sector recorded the highest average debt ratio at 36.2 percent, closely followed by Real Estate (35.4 percent) and Media & Telecommunications (35.3 percent), while the Technology sector reported the lowest at 16.5 percent. The relatively high debt ratios in these sectors can likely be attributed to their substantial capital investment requirements.
 > Click on the image to enlarge it
 > Click on the image to enlarge it
Impairment test
Causes of triggering events
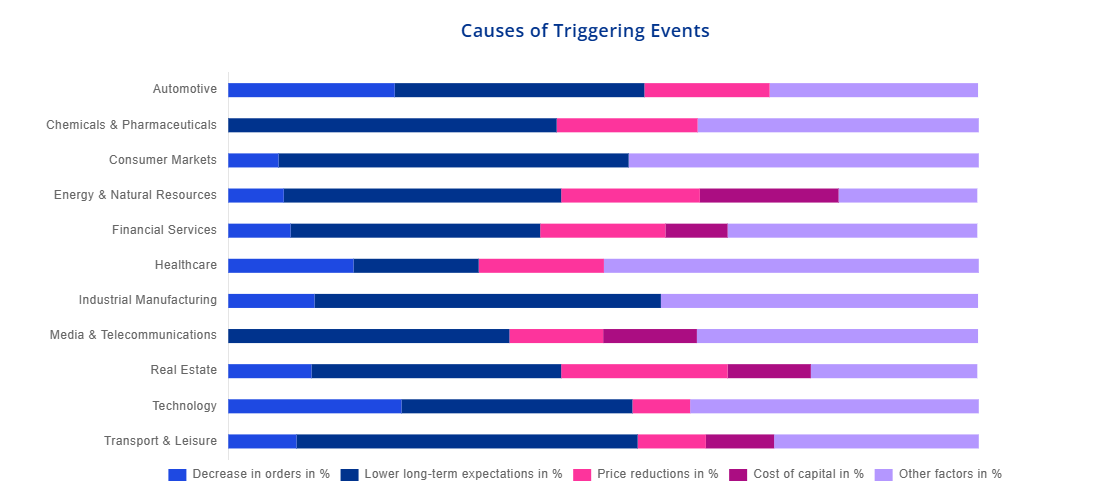
In accordance with IFRS, a goodwill impairment test is conducted annually as part of the financial reporting process. Additionally, around 38 percent of participating companies performed an impairment test during the survey period due to a triggering event.
The underlying reasons for triggering an impairment test vary significantly among participating companies and are largely industry-specific. Across all sectors, the most frequently cited reasons include deteriorating long-term expectations and other factors.
 > Click on the image to enlarge it
Strengthen your valuation processes with KPMG
Discover how KPMG Switzerland supports executives and finance leaders in making value-driven decisions. From strategic valuation to precise execution, we provide comprehensive expertise.
Our Experts


Related articles and further information
FAQ: What do the cost of capital parameters show?
The weighted average cost of capital (WACC) is the average rate of return required by all investors and is calculated as a weighted average of the cost of equity and debt, where the weights are the respective proportions of the market values of equity and debt in the total company value. The WACC represents the return from an alternative investment appropriate for investing in the company being valued.
The beta factor measures how much an individual security fluctuates in comparison to the market portfolio. It represents the valuation-relevant, company-specific risk measure.
The beta factor is a crucial component in determining the cost of equity. According to the capital asset pricing model, the required return is composed of the risk-free rate and the risk premium, the latter being the product of the general market risk premium and the company-specific beta factor.
The market risk premium represents the return required by an investor for holding a market portfolio above the risk-free rate. It is a part of the investor's required total return, which is explained using capital market pricing models.
The capital market-oriented market risk premium can be determined by calculating the differential return between investments in a representative market portfolio – consisting of risky company shares (stocks) – and risk-free investments. It can be based on both historical and forward-looking data. Thus, the market risk premium is not a parameter that can be directly observed on the capital market.
The cost of equity for a company represents the return that equity investors – investors or shareholders – expect for their investment in the company. To derive the cost of equity, empirically observable capital market returns for corporate investments in the form of stock portfolios are particularly relevant.
These returns compensate overall for the current consumption foregone by shareholders and future monetary depreciation, as well as the assumption of entrepreneurial risks, since an investment in companies and corporate shares is characterized by uncertainties.
Therefore, the total return can fundamentally be divided into a return component for the compensation of the temporal provision of capital – known as the “risk-free rate” – and a risk premium demanded by shareholders due to the assumption of entrepreneurial risk.
The cost of debt refers to the return demanded by debt holders.
The debt ratio is calculated as the ratio of the market value of (net) debt (interest-bearing assets and liabilities) to the market value of total capital.
The total return of the capital market is derived from empirically determined stock returns – both historical and forward-looking – for the representative market portfolio. Using capital market pricing models such as the capital asset pricing model, the total return can be explained and divided into individual components: the risk-free rate and the market risk premium.